How Much Does Identity-Theft Protection Cost? A Current US Price Reference
Identity-theft protection is priced in a way that makes comparison unusually awkward. Some providers advertise a monthly figure that only applies if you prepay for a year. Some advertise a first-year price that rises at renewal. Some quote one insurance limit, others quote two. The result is that four plans can be presented at similar-looking monthly numbers and cost meaningfully different amounts over two years.
This page is a price reference, not a recommendation. Every number on it came off the provider’s own page, on the date recorded under Sources and Methodology. If you are trying to decide whether to pay at all, that is a different question and we answer it separately in is identity-theft protection worth it. This page is about what the money is.
The short answer
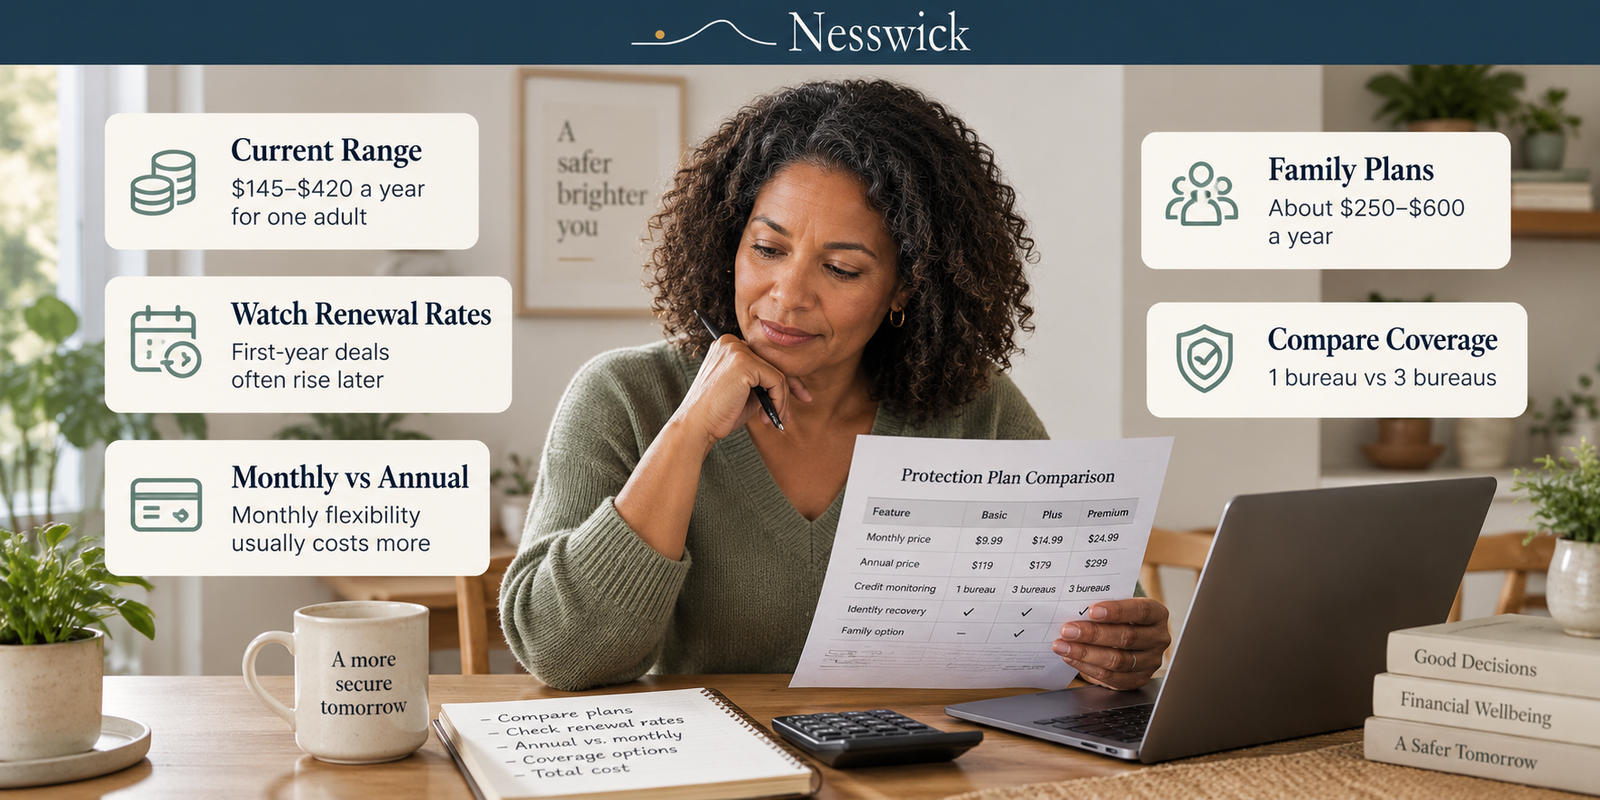
For one adult in the United States, once any introductory pricing has expired, current plans run roughly $145 to $420 a year.
The low end is Aura’s individual plan at $144 a year when billed annually. The high end is LifeLock Total at $419.88 a year at its renewal rate, or IdentityForce UltraSecure+Credit at $418.80 a year if paid monthly.
Introductory offers sit below that range in the first year. Norton 360 with LifeLock Select is $99.99 for the first twelve months. That figure is not what the product costs; it is what the first year costs.
Household plans run roughly $250 to $600 a year depending on how many adults are covered and which bureau coverage you take.
How these products are actually billed
Three billing patterns are in use, and they are not interchangeable.
Monthly-equivalent pricing that requires annual prepayment. Aura advertises $12 a month for its individual plan. That rate applies when you pay $144 up front for the year. Choosing month-to-month billing instead costs $15 a month, which is $180 across a year. The advertised number and the flexible number differ by twenty-five per cent.
Annual pricing with a monthly alternative. IdentityForce lists $199.90 a year for UltraSecure or $19.90 a month. Paying monthly costs $238.80 across a year, about $39 more.
First-year pricing with a stated renewal rate. LifeLock advertises a first-year charge on its individual plans and displays what the plan renews at. Core is $124.99 for the first year and $12.49 a month thereafter.
The practical rule: a monthly figure in an advertisement usually assumes you have paid for twelve months in advance. If you want the flexibility of monthly billing, budget more than the headline.
Current individual pricing
| Plan | First year | Ongoing annual cost | Credit bureaus |
|---|---|---|---|
| Aura Individual, billed annually | $144 | $144 | Three |
| Aura Individual, month to month | $180 | $180 | Three |
| LifeLock Core | $124.99 | $149.88 (at $12.49/mo) | One |
| LifeLock Advanced | $199.99 | $239.88 (at $19.99/mo) | Three |
| LifeLock Total | $349.99 | $419.88 (at $34.99/mo) | Three |
| Norton 360 with LifeLock Select | $99.99 | $159.99 | One |
| Norton 360 with LifeLock Ultimate Plus | $299.99 | $364.99 | Three |
| IdentityForce UltraSecure, billed annually | $199.90 | $199.90 | One |
| IdentityForce UltraSecure, month to month | $238.80 | $238.80 | One |
| IdentityForce UltraSecure+Credit, billed annually | $349.90 | $349.90 | Three |
| IdentityForce UltraSecure+Credit, month to month | $418.80 | $418.80 | Three |
Aura and IdentityForce display a single price rather than separate introductory and renewal figures. LifeLock and the Norton bundles display both.
Where an ongoing annual figure above is derived from a stated monthly rate, it is that monthly rate multiplied by twelve.
Current household pricing
| Plan | First year | Ongoing annual cost | Covers |
|---|---|---|---|
| Aura Couple, billed annually | $264 | $264 | Two adults |
| Aura Couple, month to month | $348 | $348 | Two adults |
| Aura Family, billed annually | $384 | $384 | Family plan, includes parental controls |
| Aura Family, month to month | $600 | $600 | Family plan |
| IdentityForce UltraSecure Family | $249.90 | $249.90 | Two adults monitored, plus children |
| IdentityForce UltraSecure+Credit Family | $399.90 | $399.90 | Two adults monitored, plus children |
| LifeLock Advanced, two adults, billed annually | $359.99 | $359.99 | Two adults |
| LifeLock Advanced, two adults, month to month | $431.88 (at $35.99/mo) | $431.88 (at $35.99/mo) | Two adults |
| LifeLock Advanced, two adults plus kids, billed annually | $479.99 | $479.99 | Two adults, plus children |
| LifeLock Advanced, two adults plus kids, month to month | $575.88 (at $47.99/mo) | $575.88 (at $47.99/mo) | Two adults, plus children |
| Aura Kids | $120 ($10/mo annually) | $120 | Parental controls only, not adult identity protection |
LifeLock now publishes household pricing on its public plans page, under two family tiers built on its Advanced plan. Both are displayed as a flat annual figure rather than a first-year price with a separate renewal rate, so the first-year and ongoing columns are the same for those rows. Members can also still be added to an individual plan during checkout, so the two published family prices are not the only household arrangement available.
Where a household figure above is derived from a stated monthly rate, it is that monthly rate multiplied by twelve, and the derivation is shown in the cell.
IdentityForce’s family tiers monitor two adults, with child credit activity monitoring capped at ten children.
For two adults, the arithmetic is worth doing. Aura Couple at $264 a year is $120 more than a single Aura plan at $144, so the second adult costs $120. IdentityForce UltraSecure Family at $249.90 is $50 more than UltraSecure at $199.90, so the second adult costs $50. LifeLock Advanced for two adults at $359.99 is about $120 more than the $239.88 ongoing cost of the single Advanced plan, which puts it alongside Aura; that comparison holds only at ongoing rates, because the individual plan has a first-year price and the family plan does not. Household pricing is where the ratios diverge most.
Introductory pricing, and what it becomes
Only LifeLock’s individual plans and the Norton bundles display a separate first-year price in this set. Here is the step:
| Plan | First year | Renews at | Increase |
|---|---|---|---|
| LifeLock Core | $124.99 | $149.88/yr | about 20% |
| LifeLock Advanced | $199.99 | $239.88/yr | about 20% |
| LifeLock Total | $349.99 | $419.88/yr | about 20% |
| Norton 360 with LifeLock Select | $99.99 | $159.99/yr | 60% |
| Norton 360 with LifeLock Ultimate Plus | $299.99 | $364.99/yr | about 22% |
LifeLock’s two family plans are not in this table because they do not step. Each is listed at a single annual figure that is the same in the first year and at renewal, so a household buying one of those plans is not facing an increase in year two the way an individual buyer of the same tier is.
The Norton Select bundle is the outlier. Its first-year price is the lowest of any plan on this page and its year-two price is sixty per cent higher. If you are comparing across providers, compare renewal against renewal, because a first-year price is not a price, it is an offer.
Providers also run periodic promotions below their list prices. A promotional figure at checkout is a third number again, and it is the least durable of the three.
What the extra money buys as you go up
Within each provider’s range, the step up buys a specific and identifiable thing rather than general quality.
IdentityForce: the step from a base tier to its +Credit equivalent is exactly $150 a year, at both the individual and family level. What it buys is three-bureau credit monitoring, plus a doubling of the stated insurance limit and quarterly three-bureau reports.
LifeLock: the step from Core to Advanced is $75 in the first year and $90 a year at renewal rates. It buys three-bureau monitoring and raises the stolen funds limit from $25,000 to $100,000. The step from Advanced to Total is a further $150 in the first year and $180 at renewal, and buys higher reimbursement limits rather than broader monitoring, since both plans already cover three bureaus.
Aura: there is no bureau-coverage step, because three-bureau monitoring is on every adult tier. The steps buy additional people.
So a plain reading of the pricing across all three: the most common thing you are paying more for is bureau coverage, and after that, higher insurance limits. We set out which plans include what in what three-bureau credit monitoring means, and which plans actually include it.
The insurance figures, recorded rather than compared
Each plan carries a headline coverage figure. For reference:
| Provider | Figure quoted | Structure |
|---|---|---|
| Aura Individual / Couple / Family | $1M / $2M / $5M | one identity-theft insurance figure, per adult member |
| IdentityForce base tiers | $1M | one figure |
| IdentityForce +Credit tiers | $2M | one figure, with coverage noted as varying in New York |
| LifeLock Core / Advanced / Total | $25,000 / $100,000 / $1M stolen funds, plus up to $1.05M / $1.2M / $3M reimbursement | two separate figures per plan |
Note the structural difference in the right-hand column rather than the size of the numbers. LifeLock publishes two limits per plan, the others publish one, so the headlines are not counting the same thing and cannot be ranked against each other as printed.
All of these are ceilings on categories of covered loss, subject to policy terms, conditions and exclusions. None is an amount anyone is guaranteed to receive, and none belongs in a price comparison without reading the policy summary behind it.
What the free layer costs
Nothing, and it is the reason the paid figures above are optional rather than necessary.
A credit freeze costs $0 and blocks new credit accounts being opened in your name; it is placed separately at each of the three bureaus, and the agencies must apply it within one business day online or by phone. A fraud alert costs $0 and lasts a year. Credit reports from all three bureaus cost $0 weekly at AnnualCreditReport.com, the only federally authorised source. Recovery help costs $0 at IdentityTheft.gov.
Put against the tables above, that is a $0 baseline versus $145 to $420 a year, and the free option covers the one action that actually blocks an account rather than reporting it. Paid plans add alerting, consolidation, recovery assistance and insurance on top. Whether that addition earns its price is the separate question we answer on is identity-theft protection worth it, and the mechanics of the free steps are set out in fraud alert vs credit freeze.
Who should not pay
Anyone whose credit is already frozen at all three bureaus, who checks the free weekly reports, and who has no unusual exposure is buying convenience rather than protection. That is a legitimate purchase, but it should be made knowingly.
Nobody should buy on the strength of an insurance headline without reading the policy. Nobody should buy a first-year price without checking the renewal. And a higher price does not indicate better coverage: on the figures above, a plan costing $249.90 a year monitors one credit bureau while one costing $144 monitors three. The cheapest plan is not automatically the right one either. Price and coverage are simply not correlated in this category, which is the main reason a page like this needs to exist.
Related Resources
the only federally authorised source of free credit reports
official FTC reporting and recovery service
Affiliate Disclosure
Current relationship: Nesswick does not currently use affiliate links in this article. Product and service references are included for editorial purposes.
Sources and Methodology
This is a price reference, not a recommendation, and no provider is named as a best choice. Every price on this page was read directly from the provider’s own current official pricing page on the review date below. Where an annual figure is derived rather than stated, it is the provider’s own stated monthly rate multiplied by twelve, and the derivation is disclosed in the tables. LifeLock household pricing is now publicly listed on its official plans page and has been included in the household table accordingly; an earlier version of this page recorded that no LifeLock household price was published. Introductory pricing, renewal pricing and promotional pricing are three different numbers, and this page distinguishes them; promotional discounts are excluded from the tables because they expire. Insurance and reimbursement figures are stated limits subject to the terms, conditions and exclusions of the underlying policies and are not amounts anyone is guaranteed to receive. Free-protection details, including freeze timing, fraud alert duration and weekly free credit report access, come from Federal Trade Commission and USA.gov consumer guidance. Nesswick has not purchased, operated or tested any of these plans, and makes no claim about alert quality, support or restoration outcomes. Prices change frequently; confirm current figures directly with each provider before subscribing.
Last reviewed and verified: September 6, 2026.