What Three-Bureau Credit Monitoring Means, and Which Plans Actually Include It
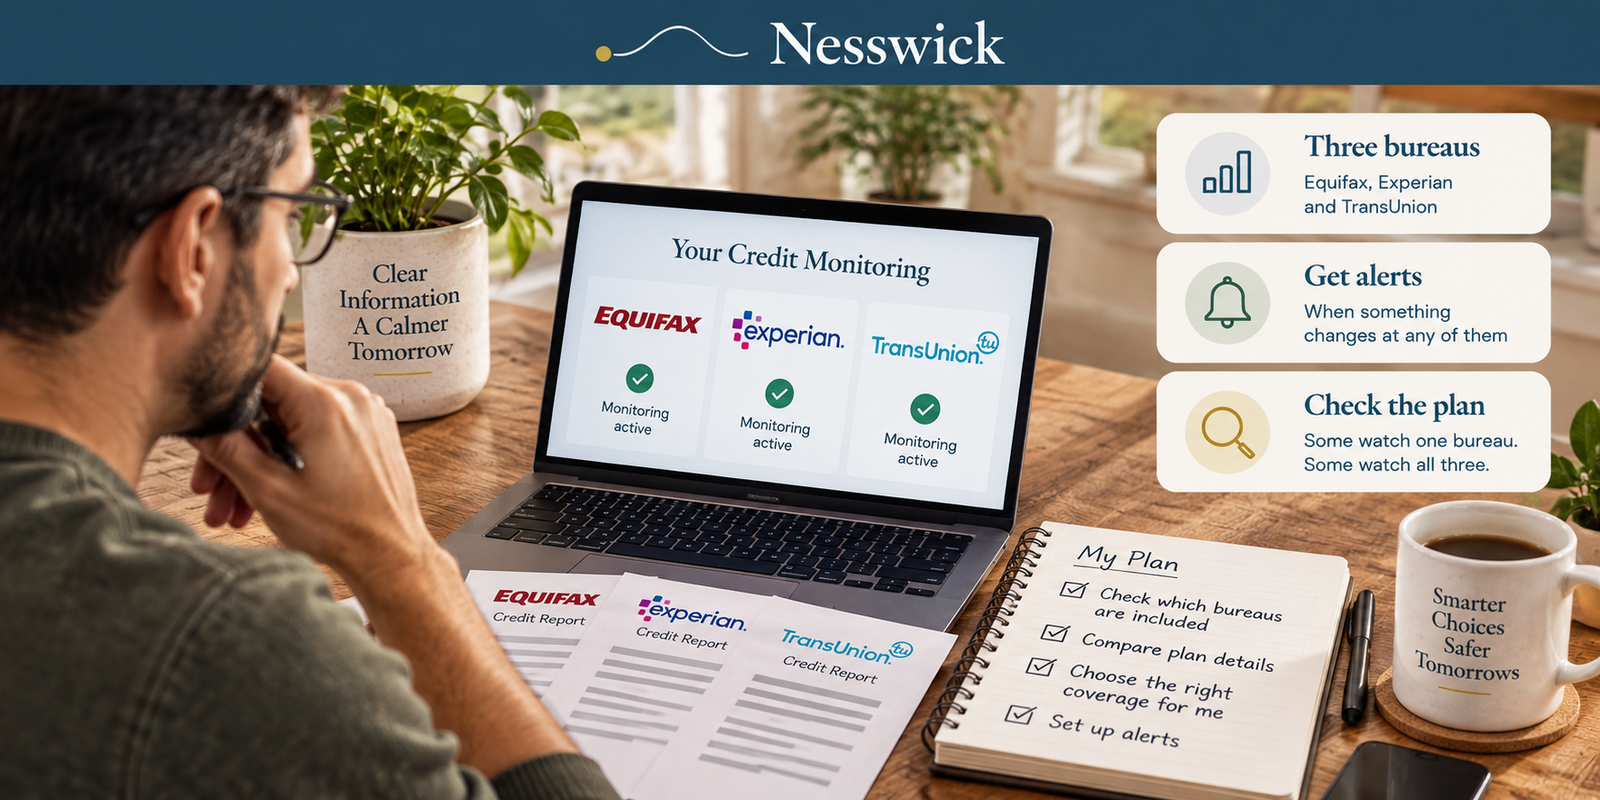
There are three nationwide credit bureaus in the United States: Equifax, Experian and TransUnion. Three-bureau credit monitoring means a service is watching your file at all three and will alert you when something changes at any of them. One-bureau or two-bureau monitoring watches a smaller part of that picture.
That sounds like a small distinction and it is not, because of how lenders report. It is also a distinction that plan names and prices do not reliably reveal. Current products range from identity-protection tiers with no credit-bureau monitoring, through one- and two-bureau monitoring, to plans that watch all three. You can currently pay $249.90 a year for an IdentityForce family plan with no credit-bureau monitoring, while Aura Individual is $144 a year and includes three-bureau monitoring. Price is not a reliable guide to what you are getting.
This page explains what the feature does, sets out which current plans actually include it, and covers what you can get for nothing.
Why watching fewer than three bureaus leaves a gap
The three bureaus are separate companies with separate files on you. They are not synchronised, and there is no rule requiring a lender to report to all three. Many report to all three, some report to two, and some report to one.
The practical consequence is straightforward. If someone opens an account in your name and the lender reports it only to Experian, a service that is not monitoring Experian will not see it. Your alert never arrives. Nothing has malfunctioned; the event simply happened somewhere the service was not looking.
The same asymmetry applies to hard inquiries, address changes and new accounts generally. Monitoring fewer than three bureaus is not worthless, and it can catch a large share of activity. But it is a partial view in a category where buyers may assume they have bought a complete one.
Which current plans actually include it
The table below is a factual record of what each provider states about its own plans on the publication-date review. It is not a ranking, and there is no recommended pick.
| Plan | Current price | Credit bureaus monitored |
|---|---|---|
| Aura Individual | $12/month billed annually ($144/year), or $15 month to month | Three |
| Aura Couple | $22/month billed annually ($264/year), or $29 month to month | Three |
| Aura Family | $32/month billed annually ($384/year), or $50 month to month | Three |
| LifeLock Core | $124.99/year; $12.49 if paid monthly | Two |
| LifeLock Advanced | $199.99/year; $19.99 if paid monthly | Three |
| LifeLock Total | $349.99/year; $34.99 if paid monthly | Three |
| Norton 360 with LifeLock Select Plus | $99.99 first year, then $189.99/year | One |
| Norton 360 with LifeLock Ultimate Plus | $299.99 first year, then $364.99/year | Three |
| IdentityForce UltraSecure | $199.90/year, or $19.90/month | None stated / no credit monitoring listed |
| IdentityForce UltraSecure+Credit | $349.90/year, or $34.90/month | Three |
| IdentityForce UltraSecure Family | $249.90/year, or $24.90/month | None stated / no credit monitoring listed |
| IdentityForce UltraSecure+Credit Family | $399.90/year, or $39.90/month | Three |
Price does not track bureau count. IdentityForce UltraSecure Family is $249.90 a year and its current feature list does not include credit-bureau monitoring. Aura Individual is $144 a year and includes three-bureau monitoring. LifeLock Core is $124.99 a year and currently lists two-bureau monitoring, while LifeLock Advanced is $199.99 a year and lists three.
Coverage structure differs by provider. IdentityForce places three-bureau monitoring on its +Credit tiers; the base UltraSecure tiers do not currently list credit-bureau monitoring. LifeLock currently lists two-bureau monitoring on Core and three-bureau monitoring on Advanced and Total. Aura lists three-bureau monitoring on every adult plan.
The cheapest tier is not reliably a one-bureau product. Current entry-level structures include no bureau monitoring at IdentityForce, two bureaus at LifeLock Core, one bureau on Norton 360 with LifeLock Select Plus, and three bureaus at Aura. Check the exact plan rather than inferring coverage from price or tier name.
IDShield is not included in the table. Its live site now displays starting prices, $14.95/month for Individual and $29.95/month for Family, and says customers can choose one- or three-bureau monitoring. However, the page reviewed does not state the exact price attached to each bureau-monitoring choice, so we have not inserted a plan-specific row that would imply a price-to-coverage pairing the official page does not establish.
What the feature costs when you buy it as an upgrade
Where broader credit monitoring is sold as a step up rather than included throughout, the current price difference between the relevant annual tiers is:
- IdentityForce, UltraSecure to UltraSecure+Credit: $150 a year, individual or family. The base tiers currently do not list credit-bureau monitoring; the +Credit tiers list three-bureau monitoring.
- LifeLock, Core to Advanced: $75 a year on the current annual pricing. Core lists two-bureau monitoring and Advanced lists three-bureau monitoring.
These are tier-price differences, not prices for credit monitoring alone; the higher tiers also add other features.
What a credit freeze does that no monitoring does
Monitoring, at any bureau count, is detection. It tells you something has happened, and it tells you afterwards.
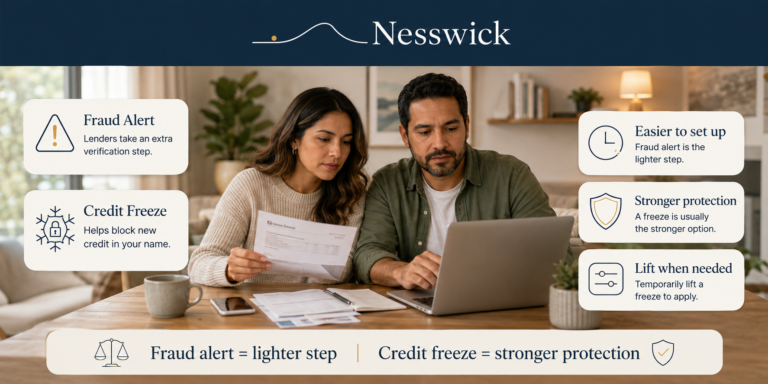
A credit freeze is prevention of a specific, narrow, useful kind. While a freeze is in place, it restricts access to your credit file and can help prevent new credit accounts being opened in your name. It is free. It has to be requested separately at Equifax, Experian and TransUnion. You lift it temporarily when you want to apply for credit yourself.
A freeze placed at all three bureaus closes the visibility gap more firmly than monitoring alone because it is preventive rather than merely alerting. The two are complementary rather than alternatives. We compare them directly in fraud alert vs credit freeze.
A fraud alert is the lighter version: free, tells businesses to take steps to verify your identity before opening new credit, and lasts one year with renewal available. Confirmed identity-theft victims can place an extended alert lasting seven years.
What free credit-report access already gives you
All three nationwide bureaus have permanently extended a programme allowing you to check your credit report from each of them once a week, for free, at AnnualCreditReport.com. It is the only federally authorised website for the free reports you are entitled to by law.
This matters for anyone weighing a paid plan, because report access and monitoring are not the same thing. IdentityForce’s +Credit tiers, for example, advertise quarterly three-bureau reports alongside three-bureau monitoring. Free weekly reports give you access without automatic alerts.
What a paid monitoring plan genuinely adds is that you do not have to remember to check manually. Weekly free reports only help if you actually look at them. Monitoring converts that discipline problem into alerts.
When three-bureau monitoring is the right thing to pay for
Three-bureau monitoring earns its cost when you want alerting across all three files and do not want to rely only on manual report checks. It can also make sense as a second layer on top of a freeze, since a freeze and monitoring do different jobs.
If you have frozen at all three bureaus and you check your free weekly reports, the marginal value of paid monitoring may be smaller.
If you are going to pay, the point of this page is simply that you should know which number you are buying. Check the plan, not the price, and check it on the provider’s own page before you subscribe. Our reference on what identity-theft protection actually costs sets the full pricing picture out in one place.
Affiliate Disclosure
Current relationship: Nesswick does not currently use affiliate links in this article. Product and service references are included for editorial purposes.
Sources and Methodology
This explainer was prepared without purchasing, operating or testing any of the plans described. The plan table records what each provider states about its own product, read directly from current official provider pages on September 12, 2026. Aura’s current pricing page lists three-bureau monitoring on its Individual, Couple and Family plans. LifeLock’s current plan page lists two-bureau monitoring on Core and three-bureau monitoring on Advanced and Total, with annual renewal prices matching the displayed annual prices. Norton’s current product pages list one-bureau monitoring on Norton 360 with LifeLock Select Plus and three-bureau monitoring on Ultimate Plus. IdentityForce’s current pricing page lists three-bureau monitoring on +Credit tiers; its base UltraSecure feature lists do not include credit-bureau monitoring. IDShield’s live site now displays starting prices and a choice of one- or three-bureau monitoring, but the page reviewed does not establish the exact price for each monitoring choice, so IDShield is discussed but not inserted into the plan-specific comparison table. Free-report details come from the Federal Trade Commission and AnnualCreditReport.com. The table is a factual record rather than a ranking; no plan is recommended. Pricing and plan structure change, so confirm current figures directly with each provider before subscribing.
Last reviewed and verified: September 12, 2026.
Sources Referenced
- FTC - Free Credit Reports
- AnnualCreditReport.com
- Aura - Official Pricing and Plans
- LifeLock - Official Plans and Pricing
- Norton - Norton 360 with LifeLock Select / Select Plus
- Norton - Norton 360 with LifeLock Ultimate Plus
- IdentityForce - Official Plans and Pricing
- IDShield - Official pricing / plan information